Labuan FSA Tightens the Screws: Business Restrictions on 35 Licensed Entities & What It Means for You
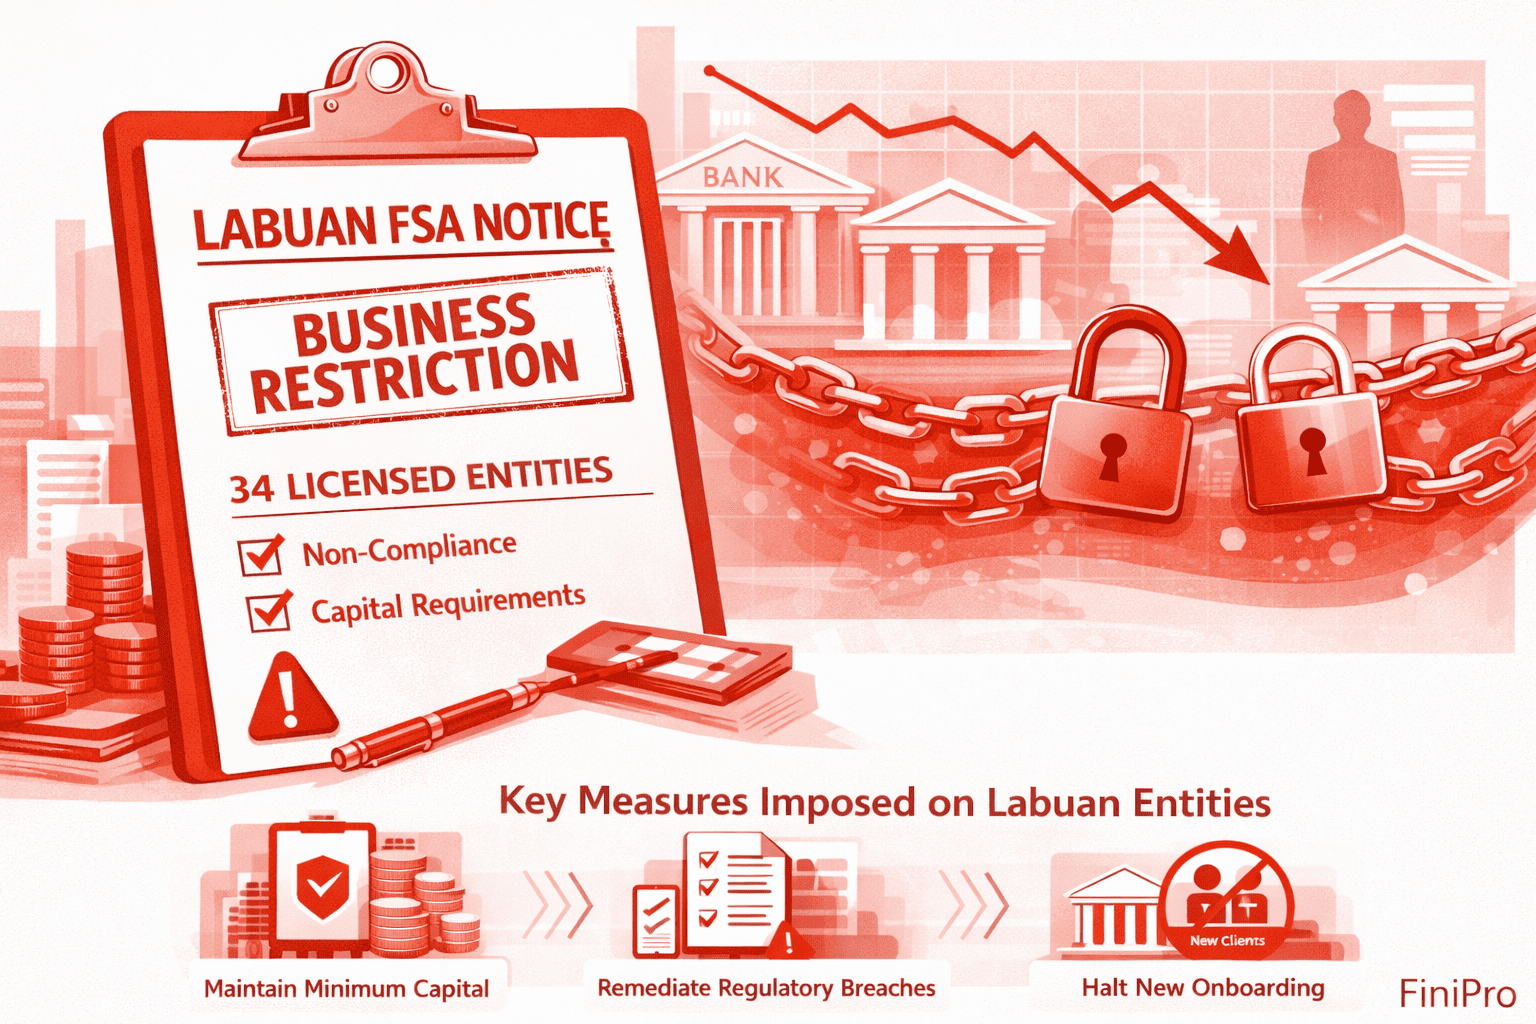
In a significant move on 22 December 2025, the Labuan Financial Services Authority (Labuan FSA) issued a public Investor Alert imposing business restrictions on 35 Labuan licensed entities.
The regulator cited non compliance with minimum capital requirements and other regulatory obligations as the primary trigger. This is not a minor technical update buried in a handbook; it is a highly visible enforcement signal.
For operators in fintech, brokerage, fund management, and insurance, the message is clear: while Labuan remains a commercially viable jurisdiction, the era of “passive” or “light touch” compliance is over.
At FinPro Consulting, we are helping clients navigate this shift. Here is our breakdown of what the notice means, why it impacts your ability to secure banking, and how to keep your structure off the enforcement list.
What Labuan FSA Actually Announced
The Labuan FSA’s notice explicitly states that business restrictions were imposed pursuant to Section 193 of the Labuan Financial Services and Securities Act 2010.
The operational consequence is severe:
The affected entities are not allowed to carry out their respective licensed activities until the issues of non-compliance are resolved.
This is not a warning letter; it is a hard stop on business operations.
Who was targeted? The 35 entities span the full spectrum of the Labuan International Business and Financial Centre (IBFC):
- 20 Money Brokers (Forex/Derivatives)
- 5 Fund Managers
- 3 Investment Banks
- 2 Insurance Brokers
- 2 Commodity Trading Licensees
- Commercial Banks & Securities Licensees
This breadth suggests the regulator is applying a baseline expectation across all business lines: minimum capital is not optional, and regulatory reporting must be maintained.
What “Business Restriction” Means in Practice
Many founders assume a restriction is just a bureaucratic flag. In reality, a “business restriction” creates immediate friction in four critical areas of your operation:
- Client Onboarding Halted: You cannot legally accept new clients, open new accounts, or sign new mandates.
- Banking Freeze: Existing banks and EMIs monitor regulator alerts. A restriction status can trigger an immediate compliance review, leading to frozen accounts or offboarding.
- Counterparty Risk: Liquidity providers, payment partners, and introduce brokers will likely pause relationships to avoid regulatory contagion.
- License Revocation Risk: Failure to remediate the restriction often leads to the next step: license suspension or total revocation.
The Core Issue: “Paid-Up” vs. “Unimpaired” Capital
The most common failure mode we see at FinPro is confusing “paid-up capital at licensing” with “capital maintained at all times.”
Labuan FSA rules (and recent 2025 guidelines) require that minimum capital must be unimpaired by losses.
- Money Brokers: You must maintain RM 500,000 to RM 1.5 million (depending on scope) at all times.
- Fund Managers: You must maintain RM 300,000 at all times.
The Trap: If your company has RM 500,000 in share capital but has accumulated RM 200,000 in operational losses, your effective capital is only RM 300,000. You are now non compliant.
Why This Matters for Banking & EMI Onboarding
If you are applying for corporate accounts with Tier-1 banks or EMIs in Singapore, Hong Kong, or Europe, this enforcement notice changes the game.
Risk teams at financial institutions use public enforcement lists as negative screening artifacts.
- Before: They checked for sanctions and adverse media.
- Now: They check if your jurisdiction is enforcing rules.
A public restriction list makes onboarding harder for marginal structures but easier for well run entities. Banks prefer clients who can demonstrate they are on the right side of a strict regulator.
[Read More: How to open a corporate bank account for a Labuan Entity]
Action Plan: 4 Steps to Protect Your License
If you operate a Labuan structure, use this news as a prompt for a 48 hour internal audit.
1. Capital Health Check
Do not rely on last year’s audit. Check your management accounts today. Is your paid-up capital intact and unimpaired by losses? If you are close to the threshold, inject fresh capital immediately.
2. Verify Regulatory Reporting (SIS)
Labuan FSA now uses the Supervisory Intelligence System (SIS). Ensure your team has valid login credentials and that all quarterly/annual filings have been submitted correctly.
3. Review AML & KYC Controls
The enforcement notice referenced “other regulatory requirements.” Ensure your AML policy isn’t just a document on a shelf. Do you have evidence of screening for your last 10 clients?
4. Prepare a “Compliance Pack” for Banks
Be proactive. Prepare a summary that includes your latest capital proof, good standing certificate, and a clear business model narrative. This helps maintain confidence with your banking partners.
How FinPro Consulting Can Help
The era of the “paper license” is over. Serious businesses need integrated support that bridges licensing, compliance, and banking.
We can assist you with:
- Regulatory Health Checks: A rapid assessment of your capital and reporting status.
- Remediation Plans: Helping restricted entities restructure and restore good standing.
- Bank Onboarding: leveraging our network to connect compliant Labuan entities with top tier banking and EMI partners.
Don’t wait for a notice letter.
👉 Contact FinPro Today for a Confidential Consultation